All Categories
Featured
Table of Contents
The interview with the credit counselor need to consist of a conversation on the root cause of your financial obligation and you need to be offered resources that will improve your total financial circumstance. If you don't qualify for a financial obligation management program significance you don't have sufficient income to manage your expenses counselors will direct you toward another service, which might be financial obligation settlement or personal bankruptcy.
If you discuss your budget plan with a counselor and there isn't money readily available to manage expenses, the counselor needs to recommend you that financial obligation management won't work.: The counselor may determine that you've simply been negligent about spending and can eliminate the debt yourself by doing a better job with budgeting.
: If your earnings can't support your debt, you might be a candidate for financial obligation settlement. This program lets you pay back less than you owe, but your credit rating will tank, and you might stack up late fees throughout the negotiations with your lenders. This method typically includes securing a loan at a lower rate of interest to pay off unsecured financial obligation.
Effective Strategies to Pay Down Interest Debt in 2026
Once again, the counselor's task at nonprofit firms is to come to a service that fits your circumstance, not to offer you on one method over the other. If you disagree with the option offered, ask why that is the very best option, or contact another counseling firm and see if they concur.
MMI is a happy member of the Financial Counseling Association of America (FCAA), a nationwide association representing financial counseling companies that provide customer credit counseling, housing therapy, student loan therapy, insolvency therapy, debt management, and different financial education services.
Financial obligation is an unfortunate truth of life for lots of Americans. Taking on debt or borrowing money that you promise to pay back doesn't necessarily need to be a bad thing. In truth, it can be a primary step toward monetary growth and stability, like when you utilize a trainee loan to get a college degree or get a home loan to buy a home.
Why to Find 2026 Financial Relief Help Immediately
Credit card financial obligation and payday loans, for example, typically come with high interest rates, and can lead to a never-ending cycle of borrowing. Debt relief normally refers to any products, services or tools that can assist you lower or manage your financial obligation, whether through expert help or on your own.
In some cases the "relief" these options offer comes in the form of lower rates of interest, lowered monthly payments or having part of your balance forgiven. Financial obligation settlement business, likewise understood for describing themselves as "debt relief" companies, are also a choice, nevertheless their titles can be deceptive. Lenders are not required to accept settlement offers and, if they do, that unfavorable mark financial obligation not fully paid remain on your credit report for seven years.
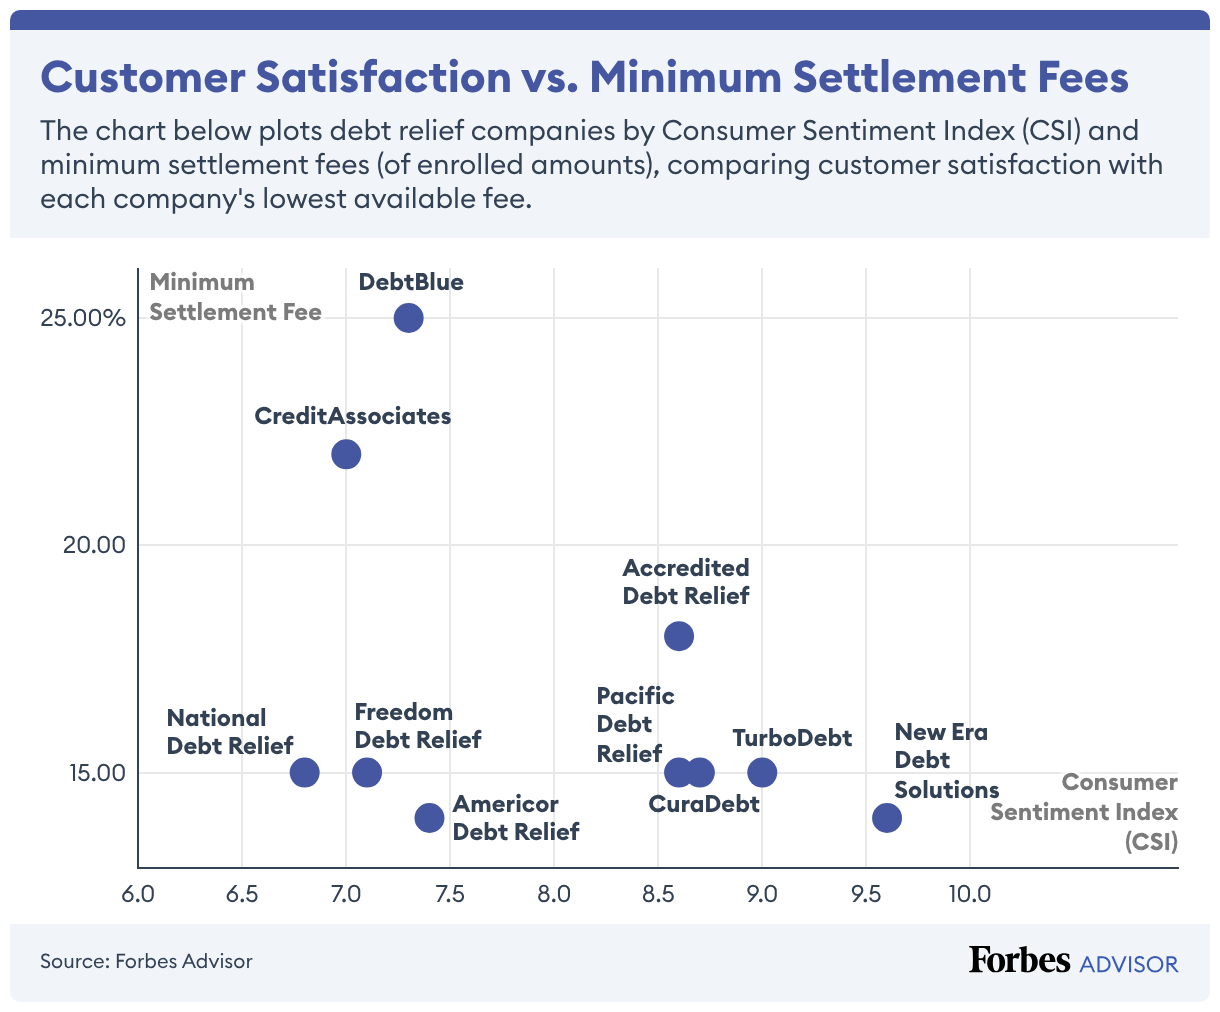
You prevent responding to calls or opening mail for worry of being called about unsettled financial obligation. If you're not exactly sure how you'll handle your financial obligation commitments, or you're seeming like you'll never be debt-free, think about these advantages of pursuing debt relief: The majority of not-for-profit companies offer credit counseling sessions totally free. Just make sure to check, because some companies might need payment for specific services.
Complete Guide to Lowering Debt in 2026
Certified credit therapists can help customers construct an economical budget, understand their debt-relief alternatives and tidy up their credit reports. These counselors do not just use a quick fix, they can promote long-lasting financial stability by increasing clients' monetary literacy. Some financial obligation relief choices, such as working out a lump-sum settlement with your loan providers, could lead to having as much as 50% of your balance forgiven.
An extreme debt relief alternative, like bankruptcy, can give you a monetary reset by forgiving or lowering financial obligation, and even stopping your loan providers' foreclosure or foreclosure efforts. Some debt-relief choices can help you get on much better terms with your lending institution, or discover ways to stop them from making continuous contact.

Latest Posts
Choosing Qualified Credit Relief Providers
2026 Credit Consolidation Analyses
How to Get 2026 Financial Hardship Assistance